Address
Level 24, Imazium,
No. 8 Jalan SS21/37, Damansara Uptown, 47400 Petaling Jaya, Selangor Darul Ehsan
Contact
+6 03 7733 1697
[email protected]
Address
Level 24, Imazium,
No. 8 Jalan SS21/37, Damansara Uptown, 47400 Petaling Jaya, Selangor Darul Ehsan
Contact
+6 03 7733 1697
[email protected]

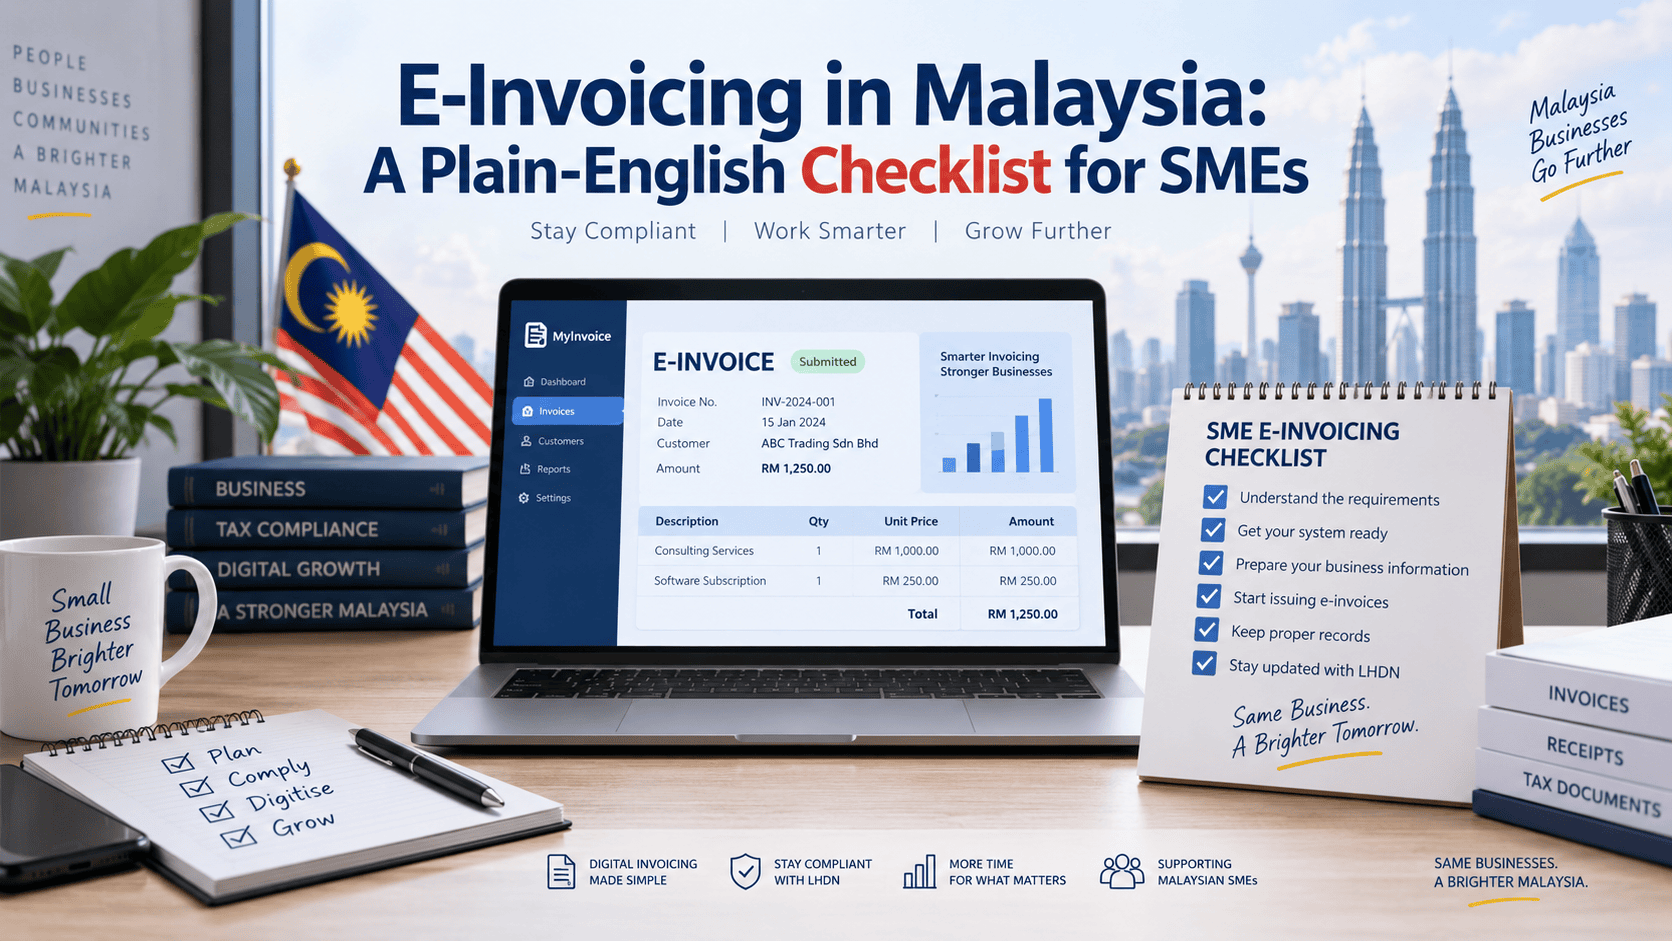
Reflects LHDN’s e-Invoice Guideline v4.8 (30 August 2026), e-Invoice Specific Guideline v4.9 (7 September 2026) and General FAQs (updated 4 September 2026).
E-invoicing in Malaysia is now live for most medium and large businesses, and the rules changed again in 2026. This e-invoice Malaysia checklist explains who still has to comply, how
MyInvois works, what your system needs to produce, and the mistakes that trip SMEs up. Everything here follows the latest guidance from Lembaga Hasil Dalam Negeri Malaysia (LHDN).
LHDN rolled out e-invoicing in four phases. Each business was placed in a phase based on its annual turnover or revenue in the 2022 audited financial statements or tax return.
| Phase | Annual turnover or revenue | Mandatory from |
| Phase 1 | Above RM100 million | 1 August 2024 |
| Phase 2 | RM25 million to RM100 million | 1 January 2025 |
| Phase 3 | RM5 million to RM25 million | 1 July 2025 |
| Phase 4 | RM3 million to RM5 million (after the exemption below) | 1 January 2026 or 1 July 2026* |
*Phase 4 originally started on 1 January 2026 for businesses with RM1 million to RM5 million in turnover. Some smaller taxpayers and businesses that started operating between 2023 and 2025 were given a later date of 1 July 2026. Since the RM3 million exemption took effect, Phase 4 in practice covers businesses between RM3 million and RM5 million.
From 1 September 2026, businesses with an annual turnover or revenue below RM3 million are exempt from mandatory e-invoicing. The threshold was raised from RM1 million following the Prime Minister’s 2026 National Day address. LHDN says more than 1.1 million micro, small, and medium enterprises benefit from the exemption.
The exemption has important exceptions. It does not apply if your business is a subsidiary of a holding company with revenue of RM3 million or more, or if a non-individual shareholder, related company, or joint venture partner crosses that line. Exempt businesses can still adopt e-invoicing voluntarily.
You can stop. LHDN’s General FAQs (updated 4 September 2026) confirm that a business meeting the exemption criteria needs no separate application or prior approval from LHDN, and may discontinue issuing e-invoices immediately. This applies whether you fully implemented, partially implemented, or never started. Exempt businesses also do not need to issue consolidated or self-billed e-invoices.
If your turnover later reaches RM3 million, you must reassess your implementation date. For businesses that cross the threshold in YA2026 or later, e-invoicing starts on 1 January of the second year after that year of assessment. For example, crossing RM3 million in YA2026 means starting on 1 January 2028.
LHDN gives Phase 4 businesses an interim relaxation period until 31 December 2027. During this window, businesses can issue a monthly consolidated e-invoice covering their transactions, submitted within 7 calendar days after the month ends. Penalties are not enforced as long as businesses follow the relaxation conditions. Full enforcement is scheduled from 1 January 2028.
The RM10,000 rule is not relaxed. Since 1 January 2026, any single sale of goods or services above RM10,000 must have its own individual e-invoice. It cannot be included in a consolidated e-invoice, even during the relaxation period. For many SMEs, this is the rule most likely to cause a compliance gap.
The relaxation period still gives Phase 4 SMEs time to build a proper setup instead of a rushed one.
MyInvois is LHDN’s platform for receiving and validating e-invoices. A supplier creates the e-invoice and submits it to MyInvois. LHDN validates it in near real time. A validated e-invoice receives an IRBM Unique Identifier Number (UIN) and a validation link, which is shown as a QR code on the invoice the buyer sees.
Every submission ends up with a status: Submitted, Valid, Invalid, or Cancelled. An invalid e-invoice has failed validation. You fix the data and submit it again.
After validation, the supplier can cancel the e-invoice within 72 hours. The buyer can request a rejection within the same 72 hours, and the supplier then decides whether to cancel. Once the 72 hours have passed, the e-invoice can no longer be cancelled. Any change then needs a credit note, debit note, or refund note that references the original e-invoice.
Retail customers do not all need individual e-invoices. When a consumer does not request one, the supplier can issue a normal receipt and later combine those sales into a consolidated e-invoice. This must be submitted to MyInvois within 7 calendar days after the month ends.
Two limits apply. A customer who asks for an e-invoice must get one. And any single transaction above RM10,000 needs its own individual e-invoice, so it cannot go into the monthly consolidated e-invoice. Certain industries and transaction types are also not allowed to use consolidation, so check LHDN’s specific guidelines for your sector.
For buyers, a validated e-invoice serves as proof of expense for income tax deduction purposes. Malaysian SST has no input tax credit, so the risk is not about claiming tax back. The risk is weaker support for business expense deductions during an audit. When buying from an exempt supplier, a normal invoice or receipt remains acceptable supporting documentation.
LHDN accepts e-invoices in the UBL 2.1 structure, in either XML or JSON. There are two ways to submit:
The guideline covers 55 data fields across eight groups, including parties, addresses, invoice details, products or services, and payment information. Some fields are optional. The ones SMEs most often get wrong are:
Missing or mismatched data is the most common reason for an invalid status. Clean customer and product master data prevents most of these errors.
Turnover alone does not decide exemption. A small subsidiary of a larger group is still in scope. Check the ownership carve-outs before stopping any preparation work.
Exempt businesses still receive e-invoices from suppliers. Larger B2B customers may also prefer suppliers who can issue validated e-invoices, since it simplifies their own records. Being exempt reduces obligations. It does not remove e-invoicing from daily operations.
A large project, contract milestone, or equipment sale can easily cross RM10,000 even when your usual ticket size is small. Each of these needs its own individual e-invoice, and the Phase 4 relaxation period does not cover them. Set your system to flag any transaction above RM10,000 automatically, rather than relying on staff to remember.
Missing TINs, outdated addresses, and inconsistent product names cause invalid submissions. Run a data audit before connecting any system to MyInvois.
Many accounting packages in Malaysia now offer MyInvois modules, but versions and extra costs vary. Get written confirmation from your vendor on which version supports MyInvois and whether it handles consolidated e-invoices, credit notes, self-billed e-invoices, and the RM10,000 rule.
Teams that miss a buyer’s rejection request within 72 hours end up issuing extra credit notes. Assign someone to monitor submission statuses daily.
Integrations fail, and portals have maintenance windows. Document how staff will switch to the MyInvois Portal and its Excel batch upload if the API connection goes down.
If you missed e-invoices or submitted incorrect ones earlier in 2026, LHDN’s e-Invoice Special Voluntary Disclosure Programme (SVDP) runs from 7 July 2026 to 31 December 2027. It lets businesses regularise these gaps voluntarily. Speak to your tax agent about whether it applies to you.
| Task | Why it matters |
| Confirm your turnover, phase, and whether the RM3 million exemption applies, including group and shareholder checks | Decides whether you must comply and by when |
| If exempt and already issuing e-invoices, decide whether to stop (no LHDN approval needed) | Avoids unnecessary cost and admin |
| Register your company and assign user roles on MyInvois | Required before any submission |
| Collect TINs and registration numbers for all regular customers and suppliers | Prevents invalid submissions |
| Map products and services to LHDN classification codes | Mandatory for every line item |
| Choose a submission route: portal, accounting software, or API | Matches effort to invoice volume |
| Flag every single transaction above RM10,000 for an individual e-invoice | Not covered by consolidation or the relaxation period |
| Set up consolidated e-invoicing for counter and retail B2C sales | Must be submitted within 7 days after month-end |
| Test submissions in LHDN’s sandbox environment | Catches data and format errors early |
| Assign daily monitoring of statuses and the 72-hour window | Avoids unnecessary credit notes |
| Document the fallback to portal and Excel batch upload | Keeps invoicing running during outages |
| Train finance and sales staff, and inform key customers | Reduces rejected invoices and confusion |
Off-the-shelf accounting software with a MyInvois module works for many SMEs. Custom integration makes more sense when invoices come from several systems, volumes are high, or billing rules are unusual. Examples include a separate point of sale, an e-commerce store, and an ERP that all need to report through one e-invoicing flow.
A custom integration can pull invoice data from each source, check it against LHDN rules before submission, and route any transaction above RM10,000 to individual issuance. It can also retry failed calls, track the 72-hour window, and keep an audit log of every UIN. That removes most of the manual rework behind invalid submissions.
Zchwantech’s Full-Stack Custom Application Development team can build middleware that connects existing ERP, accounting, or order management systems to the MyInvois API. The integration can transform data into UBL 2.1 format, validate required fields before submission, and log every response for audit purposes.
For businesses that want the integration hosted in the cloud, Zchwantech also offers cloud and infrastructure modernization, backed by a team holding more than 100 AWS certifications. The company has also built a National Digital Identity platform, which it presented to the Timor-Leste government.
E-invoicing in Malaysia now depends on where your business sits against the RM3 million exemption and its group carve-outs. Exempt businesses can stop issuing e-invoices without LHDN approval. Phase 4 businesses have until 31 December 2027 before penalties are enforced, but the RM10,000 individual e-invoice rule applies now. Use this e-invoice Malaysia checklist to plan the work. If invoices come from several systems, Zchwantech’s full-stack custom application development can connect them to MyInvois in one reliable flow.
From 1 September 2026, businesses with annual turnover or revenue below RM3 million are exempt. The exemption does not apply if a holding company, non-individual shareholder, related company, or joint venture partner has revenue of RM3 million or more. Exempt businesses can still opt in voluntarily.
Yes, if you meet the exemption criteria. LHDN’s FAQs confirm you need no application or prior approval and can stop issuing e-invoices immediately. You also do not need to issue consolidated or self-billed e-invoices.
No. If a consumer does not request an e-invoice, you can issue a normal receipt and include the sale in a consolidated e-invoice submitted within 7 calendar days after the month ends. If the customer asks for an e-invoice, you must issue one. Any single sale above RM10,000 always needs an individual e-invoice. Some industries cannot use consolidated e-invoices.
Since 1 January 2026, any single transaction above RM10,000 must be issued as an individual e-invoice. It cannot be included in a consolidated e-invoice, and the Phase 4 relaxation period does not cover it.
MyInvois assigns a Unique Identifier Number and a validation link shown as a QR code. Within 72 hours, the supplier can cancel it, and the buyer can request a rejection. After that, changes require a credit, debit, or refund note.
Failure to issue an e-invoice can be an offence under Section 120 of the Income Tax Act 1967. The fine ranges from RM200 to RM20,000, imprisonment of up to six months, or both, for each offence. Phase 4 businesses are covered by a relaxation period until 31 December 2027, subject to its conditions.
This article is for general information and is not tax advice. E-invoicing rules have changed several times; confirm your position with LHDN’s latest guidelines or your tax agent.